

TransUnion®
by TransUnion Interactive, Inc.
3.2
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.2
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
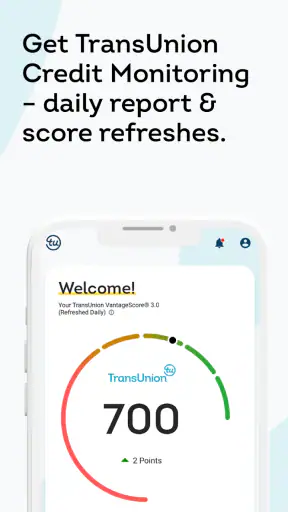
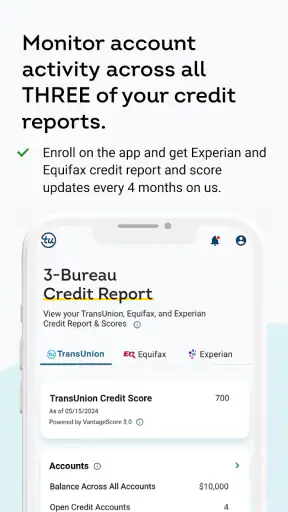
 Analysis by Getfullapps
Managing credit information is one of those tasks that is easy to postpone until a loan, rental application, or unexpected account alert makes it urgent. I spent time testing TransUnion® as a finance app, and my impression is that it works best as a compact place to check your credit position, review report information, and look at offers connected to that picture. It is free, aimed at everyone, and developed by TransUnion Interactive, Inc., so its main value is convenience rather than a broad collection of unrelated money tools.
The app has been around since January 8, 2014, and its current version is 5.8.0. That combination tells me something useful: this is not a brand-new experiment, but a long-running product that has been updated over time. It has passed one million installs and holds an average rating of 3.2 from about 8.4 thousand ratings, with roughly 3.1 thousand written reviews. Those figures suggest a service people continue to try, while also showing that the experience is not universally smooth.
How the current app fits into everyday credit management
At its core, TransUnion® is for people who want a practical view of their credit information without opening a desktop browser every time. The app brings scores, reports, and offers into one mobile experience. That sounds simple, but the arrangement is useful when you are trying to understand where you stand before making a financial decision.
I would not treat it as a complete personal-finance dashboard. It is not the kind of app I would open to plan a household budget, categorize every purchase, or manage investments. Its focus is narrower and, in my view, more helpful because of that focus. If your immediate question is “What does my credit picture look like?” rather than “Where did all my money go this month?”, this is the more relevant tool.
The first practical benefit is having a repeatable checking habit. Instead of waiting until you need financing, you can use the app as a periodic checkpoint. I find that approach more sensible than obsessively refreshing a score, because credit information is most useful when it supports a decision or helps you notice something that deserves attention.
A realistic example would be someone preparing to move into a new apartment. Before submitting an application, that person could open the app, review the available score and report information, and look for anything unfamiliar. If an account or activity seems wrong, spotting it before the application is better than discovering a problem after a landlord or lender has already evaluated the file.
The same workflow can help before shopping for a car, requesting a credit card, or refinancing existing borrowing. I especially like the idea of using the report view before looking at offers. That order matters: first understand your own position, then consider products that might be presented to you. Otherwise, an attractive-looking offer can distract you from the more important question of whether your report is accurate.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The age rating is Everyone, and the app is free to download. That makes the entry barrier low, although “free” should not be confused with “every possible financial service is included without conditions.” I would still read the terms attached to any offer and avoid assuming that seeing a product inside the app means it is automatically the best match for my circumstances.
What the score view is good for
The score is most useful as a directional signal. I use it to understand whether my general credit position appears stable and to decide whether I should inspect the underlying report more closely. A score by itself is not an explanation, so I would never stop at the number when making an important decision.
That distinction is one of the app’s most important lessons. A change can be worth investigating even when the score still looks acceptable, while a score that seems disappointing may require context rather than panic. The report is where I would look for the details behind the headline figure, particularly before applying for something that could affect my finances for years.
Another useful habit is taking notes outside the app when something changes. I would record the date I checked, the reason for checking, and any unfamiliar item that needs follow-up. This turns a casual glance into a simple monitoring routine. It also prevents the common mistake of remembering only that the score “looked fine” without remembering what was actually reviewed.
Why the report view matters more than the promotional side
The report area is the part I would prioritize. Offers may be convenient, but report information is what helps me verify whether the picture being used to judge my credit is broadly consistent with my own records. If I were helping a friend use the app, I would tell them to spend their first session understanding the report layout instead of immediately browsing financial products.
This is also where expectations need to stay realistic. A mobile presentation can make complicated credit information feel easier to scan, but it cannot remove the complexity of the underlying system. If a detail is confusing, I would compare it with my own account statements and correspondence rather than guessing from a short label.
For existing users, the current version is best viewed as an incremental continuation of a mature service rather than a completely different product. The version number, 5.8.0, indicates ongoing product evolution, but I would not assume that an update automatically changes the way every person uses the app. The central workflow remains familiar: check the score, inspect the report, and treat offers as secondary.
How I would use it without becoming dependent on it
My preferred routine would be occasional and purposeful. I would open the app after a major financial change, before a significant application, or when I receive a notification or statement that makes me question an account. I would then review the score, move into the report, and write down anything that needs confirmation.
I would not use a single app as my only source of truth. Credit information is important enough to cross-check against lender statements, account notices, and other records I already receive. TransUnion® can make the checking process more accessible, but it should support careful financial habits rather than replace them.
There is also a privacy trade-off that I would consider before installing any finance app. The convenience comes from accessing sensitive financial information on a phone, so I would use a strong device lock, keep the operating system current, and avoid checking private details on an unsecured public network. Those are sensible precautions for this type of app, even when the interface itself feels straightforward.
What has changed, what still needs work, and who should use it
The product’s history matters because it explains its position today. A finance app released in 2014 and still maintained at version 5.8.0 has had time to move beyond a one-purpose novelty. Its continued presence and more than one million installs show that mobile access to credit information remains useful to a large audience.
At the same time, the average rating of 3.2 is a reminder not to describe the experience as flawless. Ratings at that level often reflect a mixture of useful core functions and frustrating moments. In my view, the right expectation is not “this will solve every credit problem,” but “this can make routine checking easier if the app works well on my device and my expectations are realistic.”
For people who already use TransUnion’s services elsewhere, the mobile format can reduce friction. A phone is usually nearby when an important financial question comes up, and a focused app is less cumbersome than navigating a full website. Existing users may appreciate having the same general credit-checking purpose available while away from a computer.
New users should begin slowly. I would first learn where the score, report, and offers appear, then decide which parts are genuinely useful. That approach makes it easier to distinguish information I need from optional recommendations. It also reduces the chance of treating a product suggestion as personal financial advice.
The most useful trade-off is focus versus completeness: the app keeps attention on credit information, but it is not designed to replace a budgeting app, a bank app, or a full financial plan. I see that as a strength for a specific audience and a limitation for anyone hoping for an all-in-one money manager.
Where it compares with the usual alternatives
The usual alternative is checking credit information through a web browser or directly through a lender. A browser may offer a broader desktop view, which can be preferable when I need to compare several sections carefully or save documents for my records. The mobile app wins on immediacy: it is easier to open for a quick check and easier to fit into a regular routine.
A bank or card issuer’s own app may also show a score. That can be convenient because I am already signed in, but it may not give me the same report-centered experience or the same connection to TransUnion’s own services. I would compare the source and purpose of each score rather than assuming two numbers are interchangeable.
Budgeting apps are another different category. They are better when the problem is overspending, irregular bills, or cash-flow planning. TransUnion® is better when the problem is understanding credit information. If my goal were to reduce monthly expenses, I would choose a budgeting tool first. If my goal were to investigate a credit-related concern, this app would be more directly relevant.
For users who want detailed document management, a desktop browser may still be the better choice. Larger screens make long reports easier to examine, and some people prefer handling sensitive information away from a phone. I would choose the app for quick access and routine awareness, then move to a fuller channel when I need to work through a complicated issue.
Limitations and points of friction
The first limitation is that a score can encourage oversimplification. The app makes the number easy to notice, but the number is not the whole story. Users who check only the score may miss the reason behind a change or overlook an account that deserves attention. I consider that a user-behavior risk rather than a reason to dismiss the app, but it is a real weakness in everyday use.
The second is the presence of offers. They can be relevant, yet they also shift the experience from monitoring into shopping. I would not judge an offer by its placement or wording. I would compare its full terms, fees, eligibility requirements, and long-term cost independently before taking action.
The rating also makes me cautious about relying on the app during a time-sensitive application. If I needed information immediately, I would open it well before submitting paperwork rather than waiting until the last minute. That gives me time to use another access method if I encounter a login problem, delayed information, or an interface issue.
People who dislike creating accounts for financial services may also find the setup and security steps more demanding than those of a casual app. In this category, that friction is understandable, but it still affects convenience. I would rather spend extra time protecting access than treat credit information like ordinary entertainment content.
I would skip this app if I wanted detailed spending analysis, investment tracking, bill negotiation, or a complete debt payoff planner. I would also skip relying on it alone if I were dealing with a disputed account or a serious identity concern. In those situations, the app can help me notice the issue, but I would follow the appropriate official process and keep copies of relevant records.
Three practical habits that make the app more useful
First, check the report before the score becomes urgent. Many people wait until they are applying for something, which leaves little time to understand an unfamiliar entry. A calm review beforehand gives me a better chance to recognize normal activity and separate it from something that needs attention.
Second, treat offers as a comparison starting point, not a recommendation to accept. I would copy the important terms into a note, compare them with alternatives, and think about whether I need the product at all. This is a small change in workflow, but it protects the informational purpose of the app from becoming an impulsive shopping prompt.
Third, use the app after a specific trigger rather than refreshing it repeatedly. A new account, a large borrowing decision, a move, or an unexpected statement is a meaningful reason to check. This keeps the app useful without turning normal score movement into a source of unnecessary anxiety.
Those habits also answer a question many new users have: how often should the app be opened? I would not prescribe a rigid schedule. A purposeful check around important financial events is more valuable than constant monitoring, especially when a user has no particular concern to investigate.
What I would watch as the product continues
For future updates, I would watch whether the app becomes clearer about the relationship between the score, the report, and the offers. The strongest experience would guide users from a headline number to understandable context without making promotional content feel more important than accuracy.
I would also pay attention to reliability and continuity for existing users. A mature finance app earns trust when returning users can find familiar information quickly, while updates improve clarity rather than adding needless complexity. The current version shows continued maintenance, but the real test is how comfortably people can complete the basic checking workflow over time.
Accessibility and explanation are equally important. Credit language can be intimidating, particularly for someone checking a report for the first time. Clear descriptions, sensible navigation, and an easy path from an unfamiliar item to the next practical step would make the app more valuable than simply displaying more information.
My final view is positive but measured. TransUnion® is a useful free finance app for checking credit scores and report information in a convenient mobile setting, especially before a major financial decision. Its focused purpose is its main advantage, while its moderate rating, promotional offers, and the risk of oversimplifying a score are reasons to use it thoughtfully.
I would recommend it to a friend who wants a straightforward credit-monitoring starting point and is willing to verify important details independently. I would not recommend treating it as a complete financial command center or as a substitute for resolving serious account problems through the proper channels. Used as a regular checkpoint rather than an all-purpose money solution, it offers a practical way to stay more aware of the credit information that can affect everyday choices.
Pros
- Free access to credit monitoring and TransUnion credit reports.
- Clear credit score tracking helps users follow changes over time.
- Personalized alerts can flag new accounts, inquiries, or suspicious activity.
- Educational tools explain credit factors in straightforward language.
- Identity protection features may help users respond to potential fraud quickly.
Cons
- Many advanced monitoring features require a paid subscription.
- Credit scores may update less frequently than users expect.
- Some features and offers vary by country or membership plan.
- The app may promote partner products and financial services.
- Resolving inaccurate report information can still require separate follow-up.
FAQs for TransUnion®
What is the TransUnion® app used for?
The TransUnion® app is designed to help users monitor and understand their credit information from a mobile device. Depending on the available plan and region, it may provide access to credit scores, credit reports, credit monitoring alerts, identity protection features, and personalized recommendations. The exact tools can vary, so users should review the current service description before creating an account or subscribing.
Is the TransUnion® app free to download and use?
Downloading the TransUnion® app is generally free, but not every feature is necessarily included at no cost. Some basic credit information or educational tools may be available without payment, while advanced monitoring, identity protection, report updates, or additional services may require a subscription. Check the pricing, trial conditions, renewal terms, and cancellation policy shown in your country before proceeding.
Does using TransUnion® affect my credit score?
Checking your own credit information through TransUnion® is generally considered a soft inquiry and should not lower your credit score. However, the app may present offers for credit cards, loans, or other financial products, and applying for those products could result in a hard inquiry by the lender. Always read the application details carefully and distinguish between monitoring your credit and requesting new credit.
What personal information does TransUnion® require?
Because TransUnion® provides credit and identity-related services, the app may request personal details such as your name, address, date of birth, contact information, and information needed to verify your identity. It may also use security questions, document checks, or other authentication methods. Before signing up, review the privacy policy and permissions, and only enter information through the official app or website.
Why might my credit information or alerts be different from what I expect?
Credit reports and monitoring alerts depend on information supplied by lenders, creditors, and other data providers, so updates may not appear immediately. Different credit bureaus can also hold different records, and scores may vary according to the scoring model being used. If you notice an inaccurate account, unfamiliar activity, or possible identity theft, use TransUnion®’s dispute and support options promptly.

TransUnion®
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via TUIMobileApp@transunion.com, visit http://www.transunion.com, or review their https://www.transunion.com/privacy/consumer-interactive.










